Your insurer has an adjuster. Now you have one too.
We document the full extent of your loss, price it independently and negotiate the settlement your policy actually owes. Based in Alvin, serving Houston and the Gulf Coast.
- Licensed by the Texas Department of Insurance
- No fee unless your claim recovers
- Denied and underpaid claims reviewed
What a first inspection usually misses
- 01
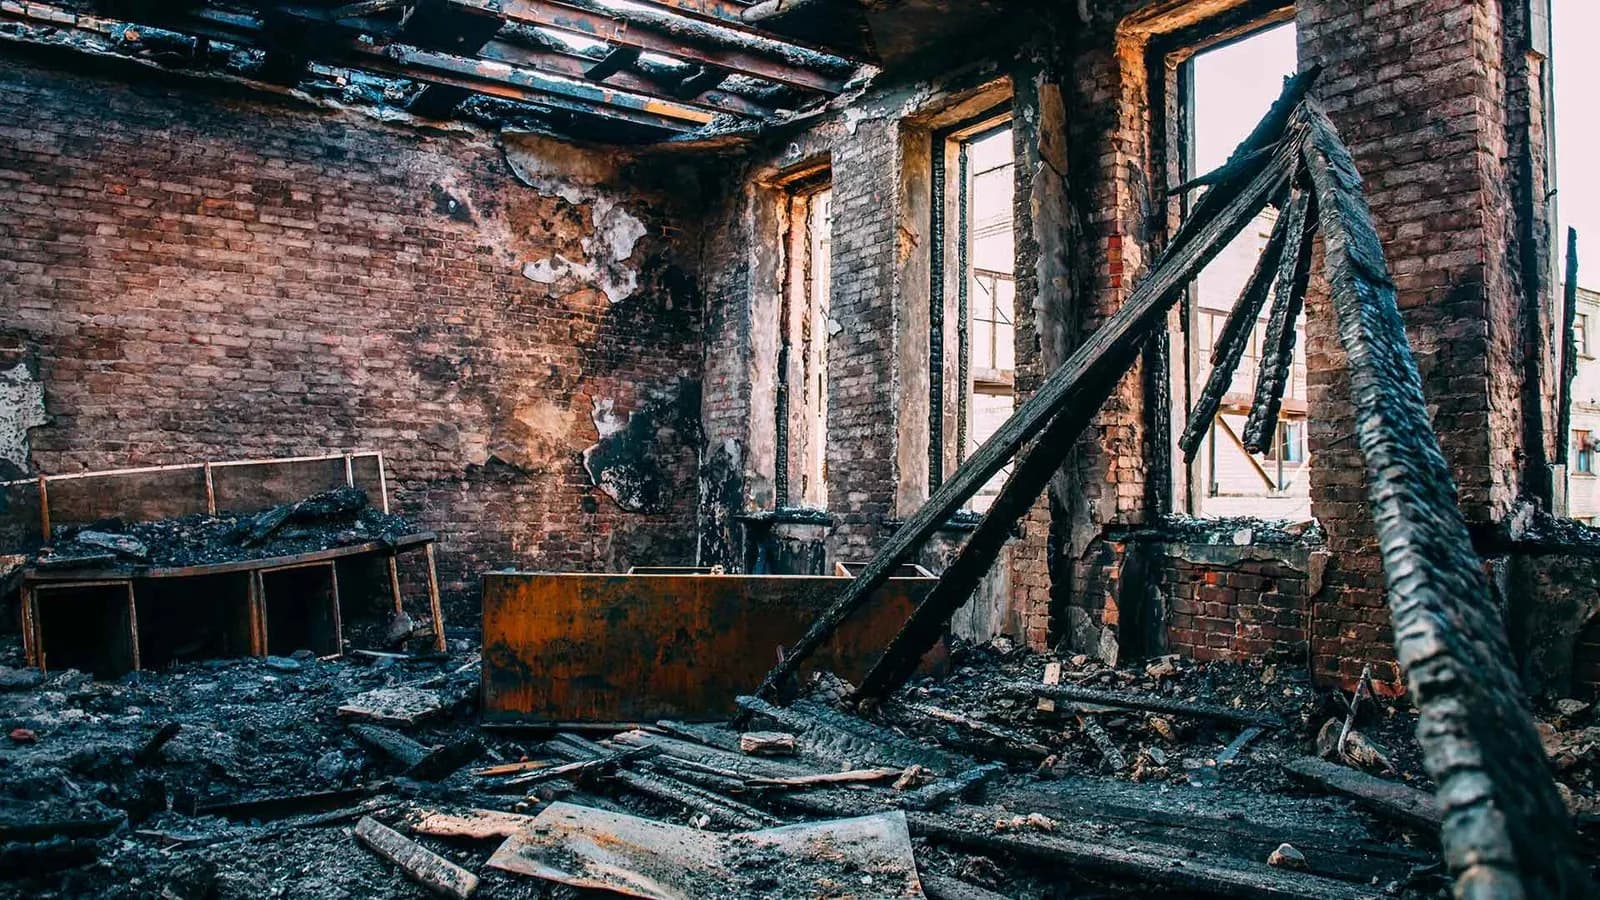
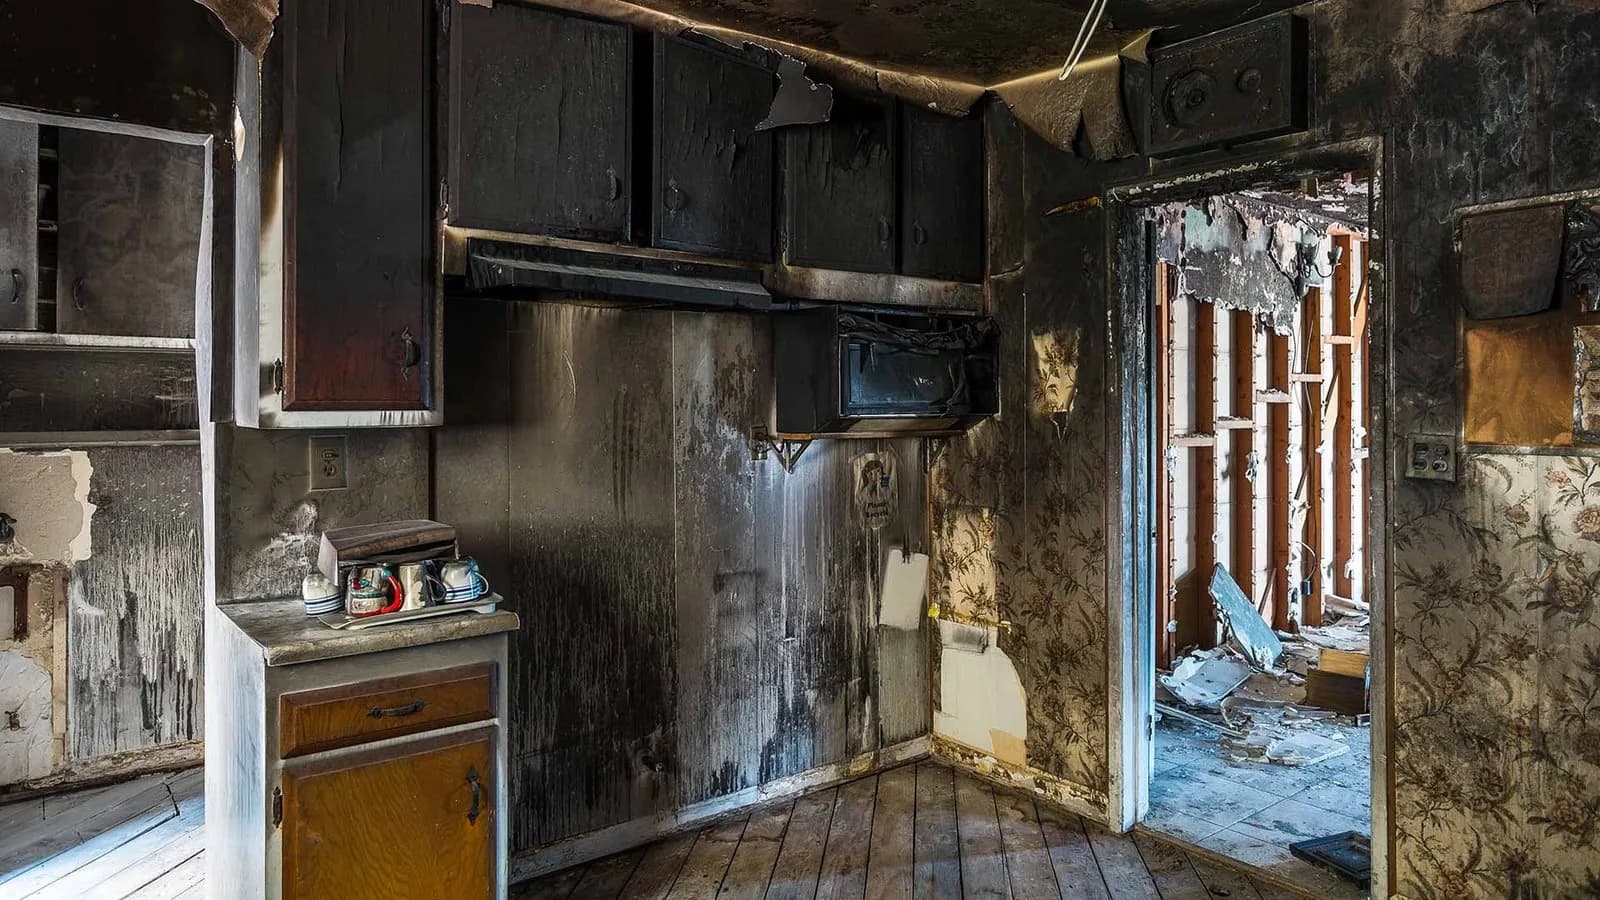
Smoke past the burn line
Smoke travels through wall cavities and into rooms the flames never reached. It shows up in testing, not in a walk-through.
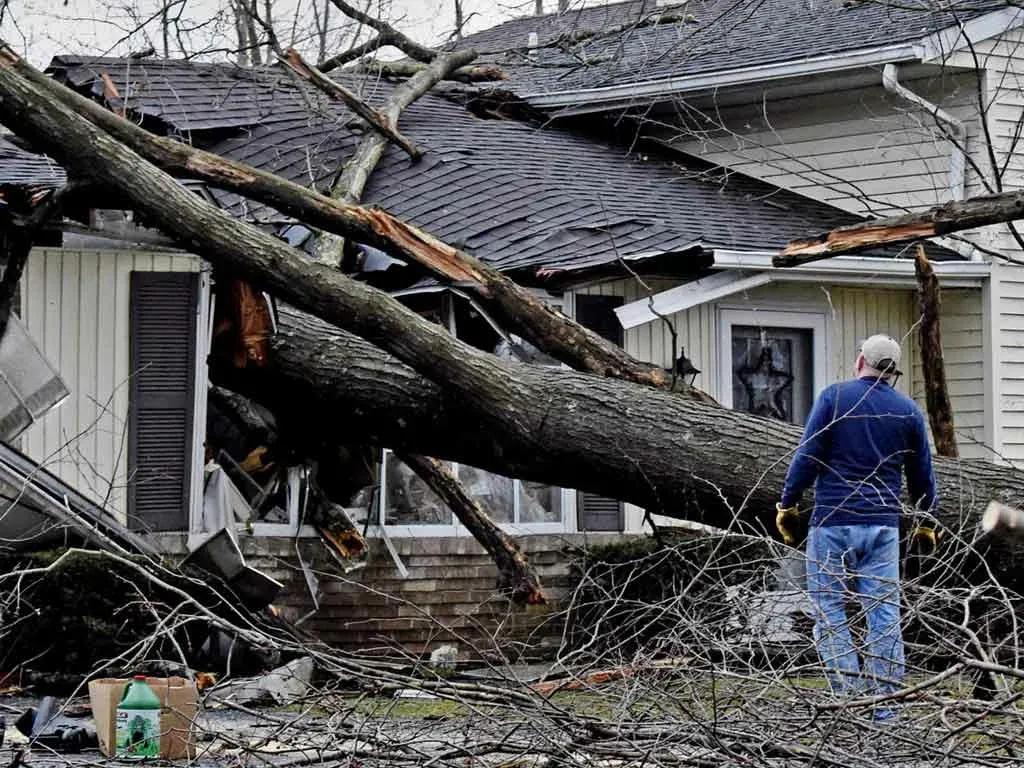
Fig. 02 · Smoke past the burn line - 02
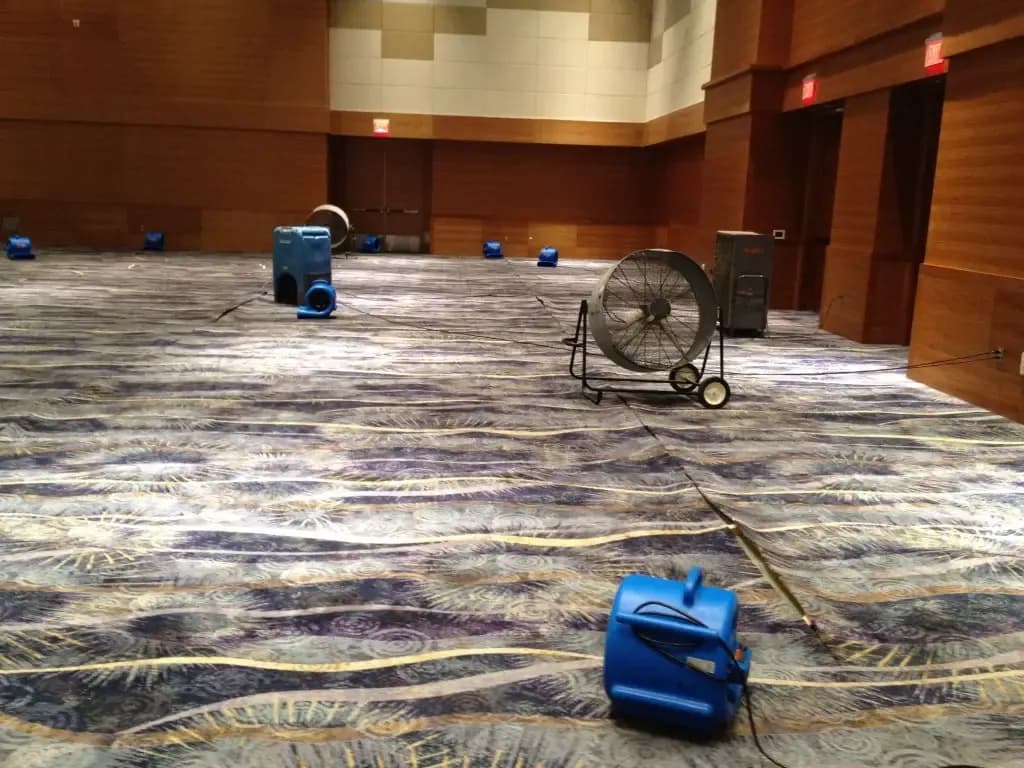
Moisture in the subfloor
Wet material can sit under a dry-looking floor long after the surface is dried. Readings against a dry standard show where it still is.
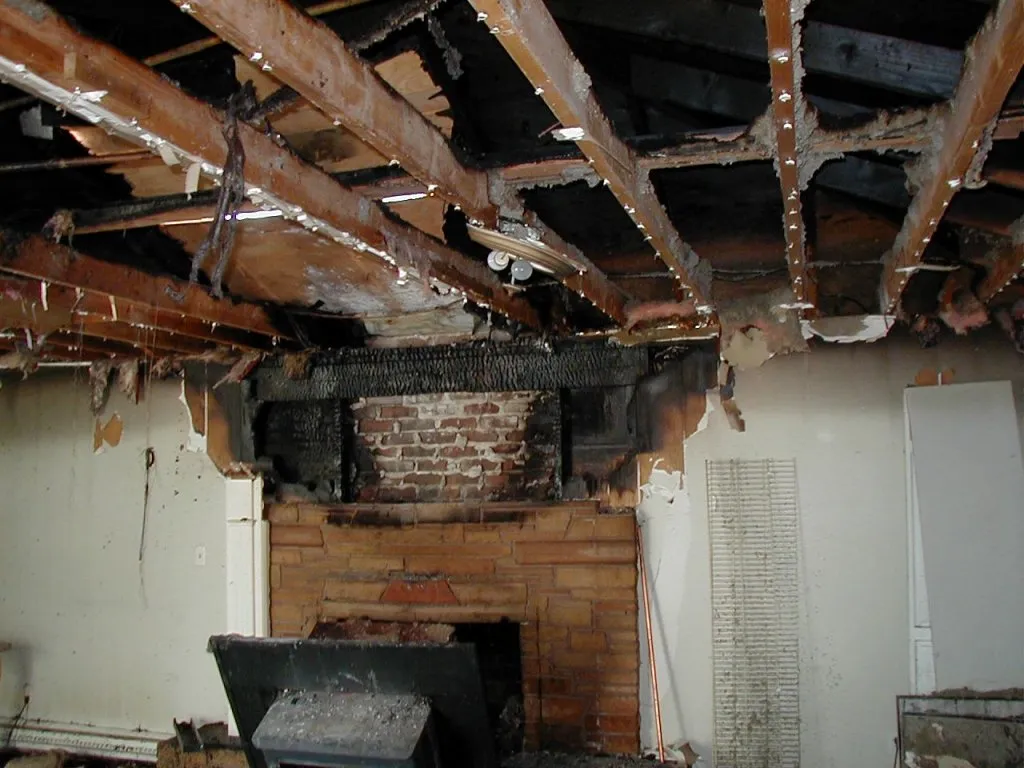
Fig. 03 · Moisture in the subfloor - 03
The roof slope nobody walked
An inspection limited to one slope can miss damage on the rest of the roof. Every slope gets its own count.
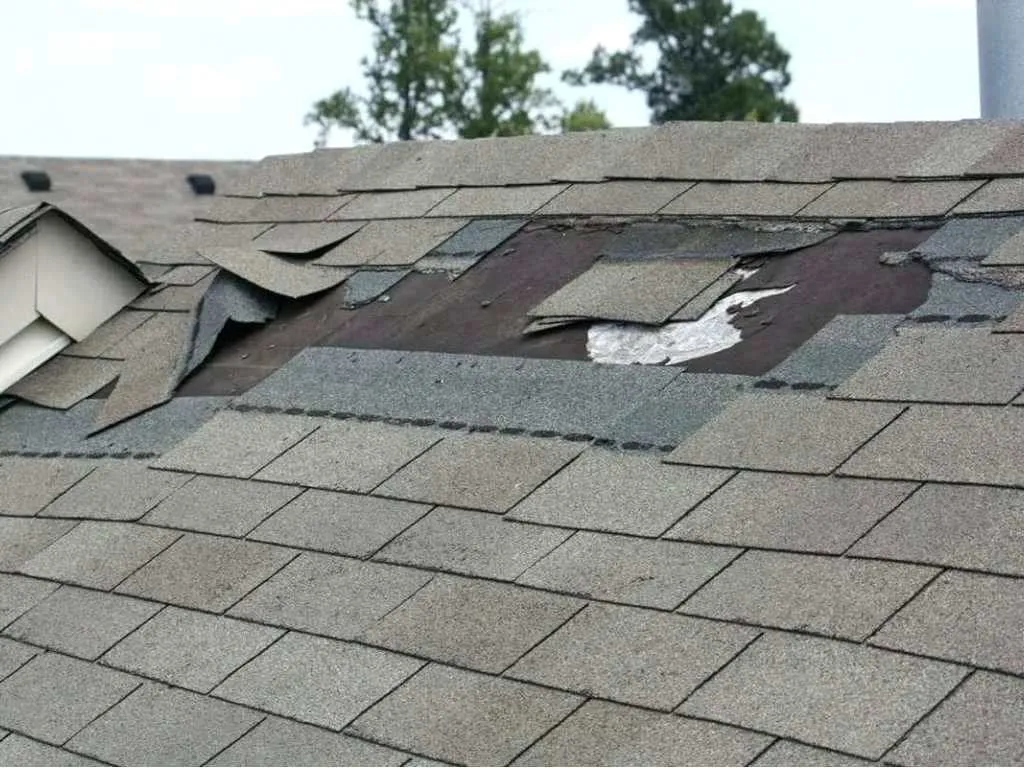
Fig. 04 · The roof slope nobody walked - 04
Required code upgrades
A rebuild can legally require upgrades the first estimate never listed. They belong in the scope from the start.
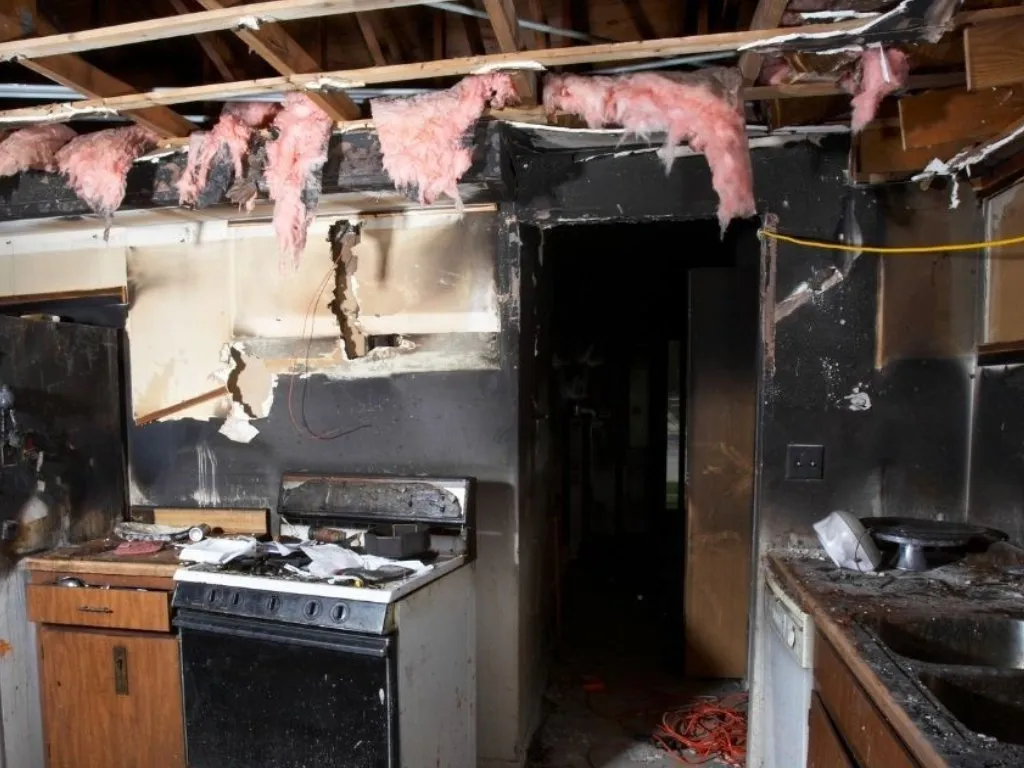
Fig. 05 · Required code upgrades
A claim is rarely settled on what you can see. The hidden categories are where scopes fall short.
See how we document a claimFire, flood, hail, water and storm claims we document
- 01Fire & Smoke DamageStructure, smoke and soot migration, contents and living expenses, documented room by room.Fire: homeowners or commercial property policy
- 02Flood DamageNFIP and private flood claims, with water line, contents and sworn proof of loss documented.Flood: NFIP or private flood policy
- 03Hail DamageSlope-by-slope roof inspection and test squares, for hail claims denied as wear and tear.Hail: homeowners or commercial property policy
- 04Water DamagePipe bursts, roof leaks and slab leaks, with moisture mapped before drying removes the evidence.Water: homeowners policy, sudden and accidental
- 05Storm, Wind & HurricaneWind, hurricane and tornado losses, with the wind versus flood split and storm deductibles checked.Wind: homeowners or TWIA windstorm policy
- 06Earthquake DamageSeismic and ground-movement losses, documented with crack mapping and elevation data.Earthquake: endorsement or separate policy
- 07Coastal SurgeStorm surge, wave impact and scour, with flood and wind documented from one site visit.Surge: NFIP or private flood policy
What happens after you call
- 01
Free claim review
Call us and we read the policy: every coverage, endorsement, sub-limit and deductible. If your claim is being handled properly, we will tell you so.
- 02
Independent inspection
We inspect the property ourselves: every roof slope, moisture readings across affected and unaffected material, thermal scanning, HVAC, attic and detached structures.
- 03
Scope, estimate and inventory
A line-by-line replacement cost estimate, plus the contents inventory and any specialist reports the file needs.
- 04
Negotiation
We present the documentation, respond in writing to the carrier's position, and work through the gap between the two estimates, through appraisal if it comes to that.
- 05
Settlement and follow-through
We track the actual cash value payment, the recoverable depreciation holdback and its deadline, and any supplemental claim as the rebuild uncovers more.
We work on contingency: an agreed percentage of the amount recovered on your claim, set out in a written contract before any work begins. There is no fee up front and no fee if there is no recovery.
We work for the policyholder, not the carrier
The adjuster your insurer sends is employed or contracted by the company paying the claim. We are licensed by the Texas Department of Insurance to represent the policyholder, and nobody else.
Houston, the Gulf Coast and South Texas, city by city
Plain answers to the letters and denials policyholders get
Public adjuster questions, answered for Texas policyholders
Answer 01
A public insurance adjuster is licensed by the Texas Department of Insurance to represent the policyholder on a property damage claim. We read the policy, inspect and document the loss independently, prepare a line-by-line estimate and contents inventory, and negotiate with your insurance company. Unlike the adjuster your carrier sends, we work only for you.
A public insurance adjuster is licensed by the Texas Department of Insurance to represent the policyholder on a property damage claim. We read the policy, inspect and document the loss independently, prepare a line-by-line estimate and contents inventory, and negotiate with your insurance company. Unlike the adjuster your carrier sends, we work only for you.
Public adjusters in Texas work on contingency: an agreed percentage of the amount recovered on your claim, set out in a written contract you sign before any work begins. Nothing is payable up front, and nothing is payable if there is no recovery.
We are based in Alvin and serve Houston, Pearland, Friendswood, League City, Dickinson, Santa Fe and the surrounding Brazoria, Harris and Galveston County communities, along with Corpus Christi and Laredo.
We can review it. A closed claim is not always a settled one, and some denials rest on a single limited inspection. What matters is the deadline in your policy and under Texas law, so a denied or underpaid claim should be reviewed promptly. We cannot promise an outcome.
Fire and smoke, flood, hail, water and pipe losses, storm and hurricane wind, earthquake, and coastal storm surge. We handle residential and commercial claims, including business interruption on commercial policies.
No. The initial policy and damage review is free, and our fee is a percentage of the recovery, paid only when your claim is settled.
Your claim keeps moving under the same policy deadlines. We take over the paperwork, estimates and calls with the carrier so the file is complete. We cannot promise how long any carrier will take.
Once you sign with us, we handle the communication with the carrier on your behalf. You still cooperate with reasonable requests, such as an inspection or documents your policy requires, and we help you prepare for them.
Do not settle for the first number.
If the offer does not cover the work, that gap can be documented. Start with a free claim review.